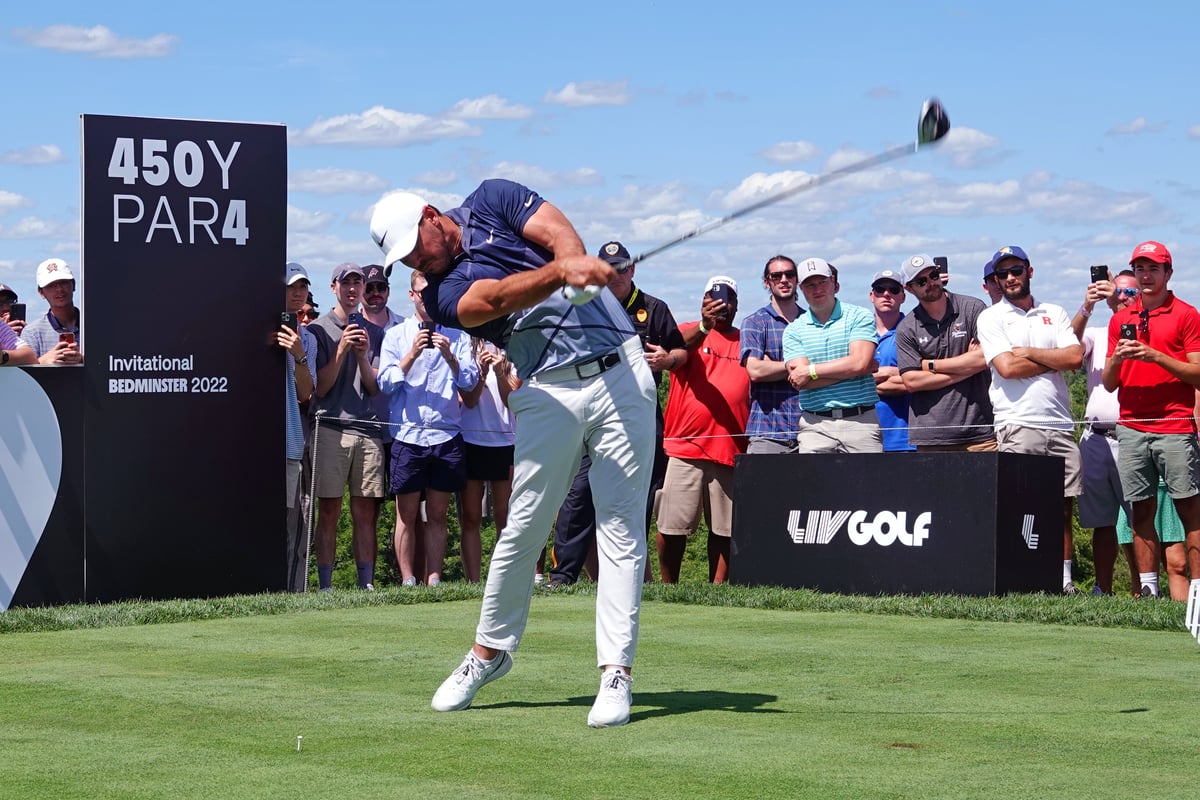
Golf’s civil war just entered its most expensive chapter yet. LIV Golf, the Saudi-backed upstart that arrived in 2022 like a sports car crashing through a country club’s front gates, has secured $300 million in financing from BC Partners Credit. The timing is perfect—like a perfectly struck 7-iron—because the circuit needs to emerge from restructuring before the 2027 season kicks off.
Let’s be honest about what this means: LIV is no longer a vanity project. It’s a fully capitalized insurgency.
The league that once seemed like a financial fever dream—luring Rory McIlroy’s friends with nine-figure signing bonuses and 54-hole tournaments played at the pace of a sprint—is now playing the long game. A $300 million war chest doesn’t get deployed on nostalgia. It gets deployed on infrastructure, marketing, and the kind of sustained aggression that makes the PGA Tour nervous enough to start merger talks.
The irony is exquisite. Traditional golf spent 150 years building prestige through scarcity and exclusivity. LIV arrived and asked: what if we just… monetized the hell out of it instead? Shorter tournaments. Guaranteed purses. Team formats that treat golf like a franchise sport.
Now, with this financing, LIV isn’t asking permission to exist anymore. It’s announcing it’s here to stay, and it’s brought money to prove it. The PGA Tour’s establishment is watching a rival that was supposed to collapse actually start building something. Whether that something is a legitimate alternative or just an expensive vanity league with better catering remains the question. But $300 million says someone believes the answer.